You Better Watch Out, You Better Not Cry, State Filing Requirement Changes Are Already Here!

Authors: Neresa Torres, Jessica Witvoet, API, AIS, AINS, AIT, and Diane Karis,AINS, CPCU
At Perr&Knight, we submit thousands of product filings (rate, rule and form) a year to the various state Departments of Insurance (“DOIs”) – and 2020 has been no exception. In fact, in addition to our normal annual volume of insurance product filings, COVID-19 has increased the number of state filings for pandemic-related submissions.
Throughout the course of this year, we have noticed a few trends in how states’ DOIs are reviewing product filings. Since we handle a high volume of submissions across all jurisdictions and all lines of business, we are able to quickly identify variations from previous years.
Here’s what we have discovered. 

States are getting pickier about the rules

Though states have always clearly articulated their filing guidelines, in preceding years DOIs were more likely to excuse minor deviations and process those filings anyway. DOIs in the past may have been inclined to give some leeway. This year, however, many states are opting to exercise their right to issue an objection or reject a filing outright if every detail is not spot on. Small errors that may have been “no big deal” in the past are now grounds for review or disapproval.
For example, Idaho is now closely scrutinizing the status of the filing in the domicile state. In the past, a “pending” entry or concurrent submission of domicile state was acceptable. Now, it is required that the program being filed is approved by the domiciliary state prior to submitting the filing in Idaho. Unless there is a reasonable explanation as to why, the filing will be rejected or subject to a 7-day turnaround for correction. If the information is not included at all, the filing is often disapproved without any opportunity for correction. Kansas has become more finicky, too, requiring each rule filing to have an accompanying form, or an objection will be issued. Other states have implemented guidance tools and checklists to ensure compliance with changing rules and requirements. For example, Massachusetts has created a four-part instruction guide to cover what is required for a filing to be considered acceptable.
The point is: don’t rely on DOIs being as forgiving as they have been in previous years. Make sure all your filing details are correct and complete.

Objections, rejections, and time-to-approval are increasing

Insurers are not the only ones experiencing administrative delays due to the pandemic. Many state DOIs shifted to remote working scenarios as well, and this has impacted their ability to issue speedy approvals. In California, for example, commercial, homeowners’, and other personal policies are taking longer to receive approval than in years past. The number of “pending” approvals has also increased.
Closer scrutiny by state DOIs is resulting in a higher number of rejections for minor issues. On the bright side, turnaround times for re-submitting are also faster. In many instances, we have seen DOIs allow re-submission within 7 to 10 days.
If your filing is rejected, correct the problem immediately and resubmit right away. Sophisticated software solutions like Perr&Knight’s StateFilings.com can help your teams keep a closer eye on filing status.

Other events impacting 2020

In addition to the disruptions caused by the pandemic, social unrest, and an election year, insurers are facing other challenges, such as recertification of the Terrorism Risk Insurance Act (TRIA), which requires all companies to update their language. Travel insurance products are also changing quickly as travel restrictions are lifted and added on a rolling basis worldwide.
This year’s regulatory requirements compel insurers to take a closer look at forms to make sure each meets the DOI’s current standards, which may have been updated recently.

Keeping track of the trends

2020 has been a year of surprise rejections for some insurance companies. It makes sense: companies only submitting a few filings per year – or who haven’t updated their product in recent years – lack the macro perspective to spot trends in DOI behavior.
When a rejection is received, it is important to determine as quickly as possible if the rejection is a unique occurrence or due to a change in a procedural requirement by the DOI. When submitting new filings, comparing against historical filings is no longer enough. Instead, it will be important to keep close track of current trends, as well as to look deeper into the DOI’s reasoning. This insight will help you avoid costly, time-consuming errors moving forward.
Internally, the Perr&Knight state filings department takes note of every rejection/objection we encounter and evaluates it to discover if it is part of a larger directional shift for that DOI, or simply a one-off. When we have questions about a particular DOI action, we contact the reviewer immediately and obtain a more thorough explanation. Because we handle such a high volume of nationwide filings, we remain in regular communication with every state DOI. These strong relationships enable us to obtain clarification on department actions that guide future filings on behalf of our clients.

Work with an experienced partner

Staying compliant today presents more of a challenge than it has in years past. Because the landscape is shifting quickly (as quickly as the insurance industry can shift), insurers are at higher risk of receiving rejections – especially those who submit a relatively low number of filings per year.
This is where working with an external insurance filings support partner can deliver a dramatic difference. Experienced state filings teams manage filings day-in and day-out. Their level of intimate knowledge of each transmittal requirement, variations between states, and regulatory expectations for each line of business can mean the difference between a smooth approvals process or being sent back to square one.
As 2020 draws to a close, the winds of change continue to shift. We expect more deviations from the status quo in the coming year. We’ll keep our clients posted on what we discover and how they can stay ahead of the game.
Questions about how to improve the efficiency of your rate filings? Our state filings experts can help.

Pet Health Insurance: Eight Key Ways to Enhance Profitability

With foreign body ingestion, poisoning, and cancer, along with being hit by car, ligament ruptures, and other accidents and illnesses, pet owners need to be prepared for the large unexpected veterinary bills that occur in treating their pet for these events. Pets are considered family members by many of us and require a significant amount of healthcare over the pet’s life, especially as the pet gets older and illnesses are more likely. In recent years, pet health insurance has been gaining in popularity and provides a way for pet owners to better manage the healthcare expenses of their pets.
For providers of pet health insurance, there are a number of ways to help enhance the likelihood of being profitable in the pet health insurance space while providing a valuable product to the pet owner.

Here are the key items that should be at the top of the list for successful programs: 

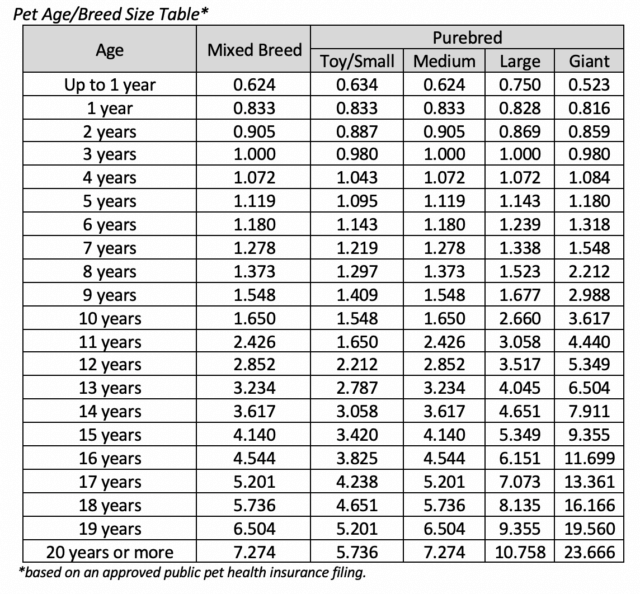
  1. Consider the impact and correlation between pet age / breed / size: While most pet health insurance writers want to focus on very young pets that will on average have better claims experience, the average age of the book of business will eventually increase as the company renews policies and the renewal of these aging pets will eventually outweigh the newer younger pets. Pet age factors are key in helping to achieve a better rate for the risk, but the risk associated with pet age is highly correlated with breed and size of dog. The table below shows an example of how pet health insurance writers are helping to maximize the correlation between these rating variables.

  1. Don’t rely on age at inception alone: Age at inception is a concept similar to whole life insurance, where your premiums do not increase as your age increases. While this may work for life insurance, it generally results in inadequate rates for pet health insurance as the average age of the book increases. Without another rating variable to compensate for the lost premium as the pet ages, the use of age at inception becomes more problematic as time goes on.
  2. Include automatic trend adjustments: Since the annual frequency and severity trend in pet claims is significant (typically ranging from 8% to 15%), a number of Departments of Insurance (“DOIs”) permit a rating factor that includes automatic trend adjustments. This allows premiums to increase over time without filing a rate increase with the state DOI. It is best to take advantage of this rating factor as it can significantly help with maintaining the profitability of the program in the states where this is allowed.

Following are a couple of examples of approved automatic trend adjustments:

  • Example 1: Due to this being health insurance for dogs and cats, loss costs will be susceptible to veterinary medical trends which we estimate to be compounding at a rate of up to 9% per year. A trend factor of up to (1+0.09)^(x/12), where x is the number of months since the effective date of this filing, may be applied to this base loss cost to account for the aforementioned inflationary effects.” 
  • Example 2: This factor is based on an expected annualized trend of 10.0% to account for the increasing cost of veterinary medical care. The formula for calculating the factor is (1+0.10)^(m/12) where m = the number of months since the base rate went into effect, and the factor in the first month of the proposed effective period equals 1.000 (i.e. m=0).
  1. Take advantage of ranges and flexibilities: Because pet health insurance is a property and casualty product and typically is filed under personal inland marine (only a handful of states are different), the DOIs in many states allow an insurance company to file subjective and experience-based rating variables for group policies, such as ranges of debits of credits, a schedule rating plan and/or an experience rating plan. It is best practice to add these where permitted to enhance rating flexibility.
  2. Don’t forget about forms: It is important to ensure your policy form has standard waiting periods and exclusions for pre-existing conditions, etc. to make sure you are not covering unexpected past injuries or illnesses. 
  1. Keep in mind that there are difficult states when it comes to profitability: Unfortunately, the biggest pet health insurance states when it comes to premium volume are also the most difficult ones to make money, such as California, Florida, New York, and Washington. These four states can sometimes make up to 50% of a nationwide book of business and the necessary rate changes to maintain profitability are often difficult to obtain with long approval timelines. While it may be enticing to write in these states due to the high growth potential, be careful as it is rare to be profitable in these states and very difficult to non-renew the business if things go south.
  2. Don’t set and forget: Pet health insurance rates need to be managed over time. A key to maintaining profitability is to take the necessary rate changes to at least achieve the target loss and expense ratio. Too often companies wait a few years before reviewing rates. This makes it very difficult to realize the rate level needed to achieve and maintain profitability.
  3. Monitor, monitor, monitor: It is important to not only understand the profitability of your book of business from an overall standpoint, but also whether your class plan rating variables are appropriately pricing the risk. Whether rating variables (such as state, deductible, coinsurance, pet age, breed, et.) are reviewed individually or with the use of predictive modeling, these analyses should be performed at least once a year to understand where the program is profitable and where rate increases are necessary to improve or maintain that profitability.

Pet health insurance is a fast-growing market with significant growth potential, but there are also a lot of ways to lose money in the process and companies can get themselves into a hole that is sometimes very difficult to dig out of.
About Perr&Knight
Perr&Knight is a leading provider of both actuarial consulting and pet insurance product development services to companies providing pet health insurance. Our consultants have assisted a number of pet health insurers with developing and maintaining a profitable pet health insurance product.

Please contact us with any assistance that is needed with your pet insurance product development.

Travel Insurers Must Pivot in the Wake of COVID-19

Authors: Crystal London, FSA, MAAA and Susan Cornett, FLMI, AIRC, CFE
As international travel restrictions remain in place, more and more Americans are planning domestic travel this summer and fall. According to the RV Industry Association, 46 million people will take road trips in the next twelve months. RV rentals and sales are also way up. This shift in focus to domestic, road-based trips means insurers must remain flexible and be prepared to offer smaller packages that align with emerging trends in travel planning.

Existing policy offerings are less relevant

Traditional travel insurance tends to cover issues impacting travel overseas, cruises, or big ticket domestic trips such as Hawaii or the U.S. Virgin Islands. As insureds take more domestic trips, especially by vehicle, expensive coverages such as trip cancellation/interruption, missed flight connection, lost baggage coverage and international medical coverage are much less relevant. Instead, insurance product development teams should shift thinking toward ancillary coverages that address the myriad of risks associated with travel by car or RV/camper.

Concentrate on road-based benefits

Travel insurance benefits in the COVID era are more nuanced than the big-ticket airline/cruise packages that were previously common. Given that more people are traveling by vehicle, ancillary coverages working in tandem with existing auto and health policies provide peace of mind for travelers spending more time in their own vehicles or rented cars, trucks and RVs.
Here are some common coverages that will be in greater demand as road trip travel increases throughout the summer and into the fall:

  • Rental vehicle damage
  • Excess medical expense
  • Emergency evacuation
  • Accidental death & dismemberment
  • Vehicle return
  • Return of traveling companion and/or minor child(ren)
  • Emergency hotel coverage
  • Hotel overbooking

Policies should address unexpected disruptions to road trips

A shift toward road travel provides an opportunity for insurers to develop additional benefits addressing the specific needs of today’s domestic travelers. As people hit the road, many bring along the family pet, creating a need for coverages such as pet emergency medical. Pet return and kennel delay insurance are also valuable should the insured have a loss and can’t get the family pet home or can’t get home in time to pick up the pet. Campgrounds may replace hotels when it comes to cancellation fees or overbooking risks, so insurers may consider offering camping-specific policies. Travelers may also require additional insurance to cover damage to rented properties that goes beyond general liability covered by vacation home rentals such as Airbnb or VRBO. All of these policies are launching points for insurers to develop creative coverages for domestic travelers.

Increasing importance of “cancel for any reason” and pandemic-inclusive policies

Because COVID-19 is still far from resolved, we anticipate travelers will remain skittish for at least the upcoming six months, if not longer. However, given the attractive prices offered by airlines and hotels, some travelers are beginning to plan trips far into the future. With the current level of uncertainty surrounding COVID-19, “cancel for any reason” policies are more attractive to consumers. When international travel does resume, unpredictable border re-openings and attraction re-openings will create a higher demand for pandemic- and epidemic-inclusive policies, as COVID-19 shifts from an “unforeseen” classification to a foreseen event and consumers will look for policies that will provide coverage.

Re-think your customer base

During this time, insurers should shift focus from airlines and cruise company partnerships to add-on coverages through car and RV rental companies. Travel insurance isn’t usually top-of-mind for domestic vacationers, so direct-to-consumer marketing efforts should also increase. Now is the time to initiate outreach to new and existing policyholders to increase awareness and urge additional domestic travel protections. Additionally, since most travelers search online for trip insurance, make sure your company is visible with coverages applicable to their shifting needs. You may not be offering appropriate policies, but your competitors likely are.

The time to act is now

If your company doesn’t currently offer a wide set of coverage for domestic travel, our experienced product development and rate development teams can help. We’ll help you discover which benefits are most important to insureds in this environment and conduct valuable competitive analysis to reveal your competitors’ actions.
In many cases, insurers already have aspects of the above coverages in place, so your company may not require a lengthy insurance product development phase to address the needs of today’s travelers. We can help you develop new coverages or adjust language or rates on existing policies to provide a better fit. Based on our deep experience as insurance consultants, our assistance with form development, rate development and state filings can accelerate your time to approval.
Travel insurers are facing spikes in service requests that are as yet not totally known. Airlines and crowded resorts are out of favor. Instead, industry experts are seeing a transition to road trips and long-term rentals. Since major revenue streams are currently stalled, insurers must make changes to keep premiums flowing. For most providers of travel insurance, this means focusing on creating a higher volume of smaller-premium offerings until more expensive travel returns to popularity, which could take years.

Talk to Perr&Knight’s insurance consulting experts to make sure your travel policies are the right fit for today’s customers.

Predictive Analytics Provide Big Gains for Small Insurance Companies

It is no secret that the amount of data in the world is expanding at an extremely rapid pace, and in a time where business is being conducted online due to COVID-19, this rapid data production is going to accelerate more than ever. Of course, this mass influx of data is only useful to companies when they have access to it.
This data gap between insurance companies will widen even more due to COVID-19 as large companies with direct-to-consumer online platforms will see increased business due to stay-at-home orders and less in-person business. The increase in online business could be used in predictive models to analyze marketing trends and gain new market share, which leads to more business to enrich pricing and claim triage models, which increases profits and the ability to gain market share. From there, the cycle will start all over again.
A large data gap already exists between large and small companies, and now the gap for online business capabilities is also growing at an increasing rate. What can small companies do to help make sure that gap does not become insurmountable?
Luckily, external data is now more readily available and easily accessed than ever before. Companies with little data (or in some cases even no data) can take advantage of external information for predictive modeling. Some examples of external data sources include:

  • Government information such as census demographics, weather databases, occupational statistics, geospatial, and property tax information.
  • Numerous industry statistics and services from advisory organizations such as ISO, NISS, or NCCI.
  • Industry information from publicly available rate filings and financial statements.
  • Quote comparison services for competitive analyses.

Misconceptions about small companies’ ability to use predictive analytics are not limited to data constraints. There is also a common misconception about the models themselves having to be extremely sophisticated. While it may be true that many companies are using such complex models, smaller companies can still benefit from the use of analytics by simplifying their scope to accommodate less data. Some examples include:

  • Creating models that assist with monitoring programs by ranking predictors with the largest impact on results. These give quick insights to help focus additional research.
  • Using simpler assumptions and grouping variable levels in order to increase the credibility of the model.
  • Combining company data with external data sources to add additional predictors to your results.
  • Consulting with industry experts to follow modeling best practices such as removing data outliers and/or missing values in order to maximize the amount of usable data and not skew results.

Not only can these scenarios be applied today to help insurer performance, but Perr&Knight has experience in assisting clients in each and every one of them. With both experienced predictive modeling personnel and industry expertise in virtually all lines of insurance, Perr&Knight is uniquely qualified to assist small companies in implementing predictive analytics to help improve insurer performance and profitability.
As the world continues to evolve technologically, so too does the sophistication of insurance products and the insurance process. It is important for small companies to modernize their approaches to help minimize the data gap in an increasingly data-driven environment.

Leverage the power of predictive analytics. Contact the experts at Perr&Knight to learn more about how your company can use data from predictive analytics to improve business outcomes.

Digital Transformation: Are You Sure You’re Ready?

Motivations behind digital transformation initiatives usually involve improving speed, cost, or quality of products or services. Migrating to the cloud, increasing mobility, implementing robotic process automation (RPA), deploying intelligent automation solutions, or capitalizing on data from the internet of things (IoT) all have the power to profoundly impact an insurance company’s competitive standing – if not their very survival.
With 67% of insurers considering implementing digital transformation initiatives over the next twelve to eighteen months[1], companies not considering these changes will soon be left behind.
However, undertaking an initiative too hastily may overlook critical organizational considerations likely to inflate project costs and jeopardize the success of the program.
Throughout hundreds of insurance technology consulting engagements, we have identified five phases comprising successful preparation for every tech project: Initiate, Design, Experiment, Prioritize, and Plan. Each is a valuable component of the process which, if executed carefully and correctly, has the potential to double the chances of success of your IT project.
In this article, we’ll cover an often-overlooked – but vitally important – aspect of the Initiate phase: determining your readiness to even begin.

The Picture Is Bigger Than You Think

Because every company’s systems are so deeply intertwined, each affects more aspects of the business than may be initially apparent. Even if equipped with good intentions, simply jumping into major structural or process changes can create serious roadblocks for other departments or processes down the line.
In our decades providing insurance technology consulting services, we have seen dozens of costly – and avoidable – challenges arise when companies implement new initiatives without adequately ascertaining the impact of their project on the whole of the organization. It’s not uncommon for organizations to discover their planned initiative reflects only a superficial portion or “end of the line” aspect of the required change, when they should plan for complementary tech upgrades or cultural impacts in other departments as well.
By “preparing to prepare,” you determine your organizational readiness to undertake any transformation – digital or otherwise. And, taking a holistic view reveals the true scope of the initiative, one that may extend well beyond initial expectations.

Conduct a Readiness Assessment

We believe so strongly in the value of determining whether organizational readiness supports – or inhibits – a project’s ultimate success that we have designed a comprehensive organizational Readiness Assessment.
Conducted during a sixty- to ninety-minute web meeting, the assessment reviews key questions about your organization to determine its level of readiness in six areas of your business: Personnel, Processes, Technology, Metrics, Governance, and Environment.
The assessment drills down into a range of relevant factors:

  • Personnel availability
  • Team skills
  • Individual and team empowerment
  • Staff commitment
  • Impact of program on processes
  • Process indoctrination
  • Benefits realization
  • Technology infrastructure
  • Software considerations
  • Interfaces
  • Metrics definitions
  • Visibility into KPIs
  • Response to met or unmet KPIs
  • Extent of existing program planning
  • Program organization
  • Program procurement
  • Program implementation & deployment
  • Program support, monitoring & evaluation
  • Physical location
  • Company culture
  • Team morale
  • Other business-specific considerations

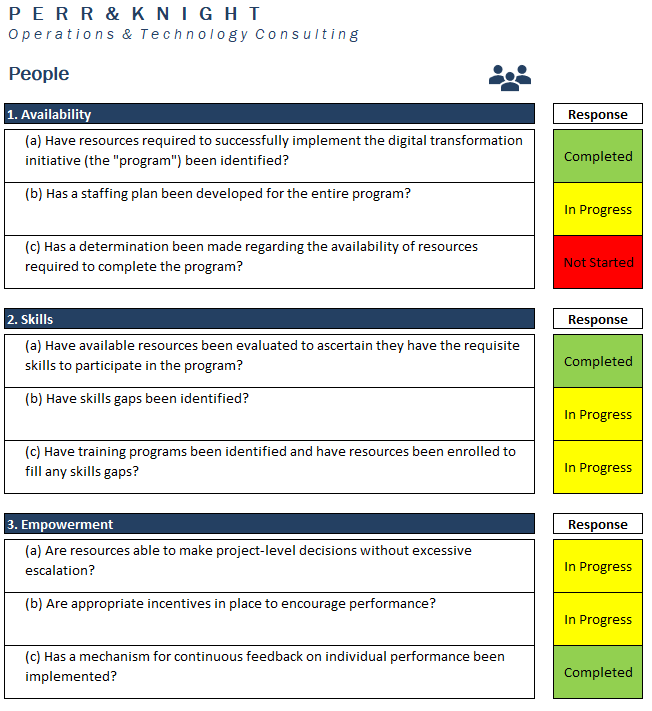
Readiness Assessment for Insurance Technology

A page out of Perr&Knight’s Digital Transformation Readiness Workbook

Answers to straightforward questions on these subjects reveal a clear picture of your organization’s strengths and weaknesses in areas with the potential to impact the result of your transformation initiative. This valuable contextual view enables your team to further develop your strategy before beginning project planning, in order to avoid playing costly catch-up later.
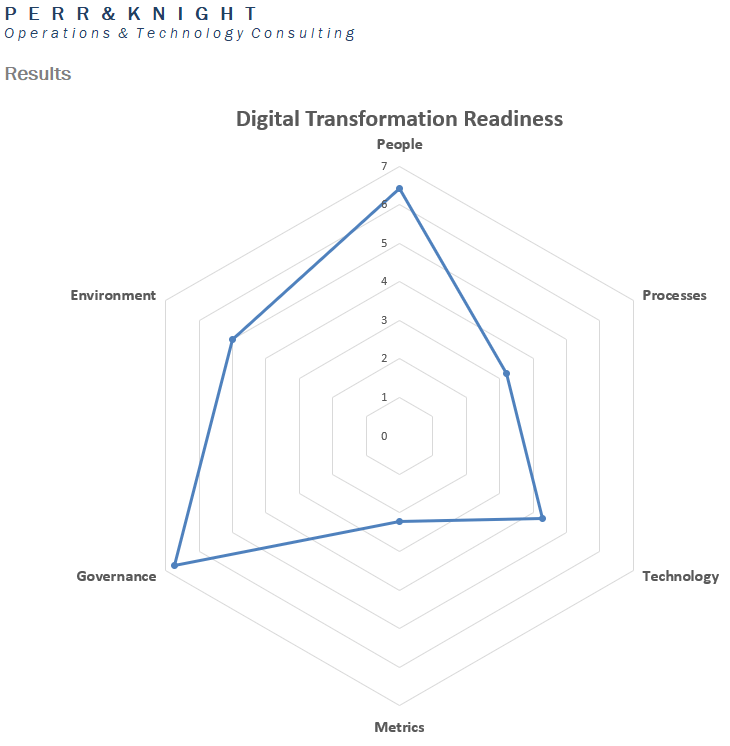
The results of this exercise create the foundation for the remaining four steps of preparation for your project. In addition to determining your level of readiness overall, this assessment provides a useful starting point to prioritize areas for work before and during your digital transformation initiative.
Readiness Assessment Results by Perr&Knight

The results area of Perr&Knight’s Digital Transformation Readiness Workbook

Preparation Is Important – But So Is a Tolerance for Risk

Successfully executing any major change requires commitment, tenacity, and a risk tolerance from leadership and the organization as a whole. To promote innovation, there must be support for experimentation and a willingness to endure the challenges of repeatedly failing, learning, and failing again before success finally takes root. The values that represent your organizational culture are crucial – if individuals are punished for failure, they will cease to experiment, and innovation will become a distant hope rather than a realized goal.
Gaining a thorough understanding of the benefits of a successful endeavor balanced against the pitfalls that lie ahead – even before approaching the starting line – gives you a much stronger chance of completing a successful digital transformation initiative and truly remake the way you do business.
To support the insurance industry’s unprecedented embrace of digital transformation, the workshop is being offered by Perr&Knight on a complimentary basis to organizations contemplating any type of transformation project. The accompanying readiness workbook and resulting assessment will be provided at the workshop’s conclusion.

Interested? Contact Perr&Knight today and carve out just ninety minutes to significantly increase the likelihood of a successful digital transformation initiative – ready or not.

[1] SOURCE: 2020 Financial Services Digital Transformation Survey, BDO

Why Stat Reporting Shouldn’t Be an Afterthought

Authors: Jason Hudson, Principal Director, Statistical Reporting Services, and Mark Nawrath, Principal Director, Account Management
When insurance companies prepare to implement new software for policy and claims administration, regulatory reporting of the data captured is an afterthought. What appear to be turnkey systems often turn out to require more retrofitting and configuration than initially expected to meet statistical reporting requirements, resulting in an increase in investment and a longer timeline to launch.
Here’s why it’s necessary to consider statistical reporting needs throughout the entire development and implementation process.

Powerful and flexible modern systems…they require more configuration

Legacy technology (early mainframe systems) demanded a ton of programming to account for every possible scenario required for policy and claims administration. Building the complex logic required to encode, transform and format data into compliant statistical plan formats was an assumed part of the implementation process.
However, when client server technology started to take off in the 1990s and 2000s, new client-server-based technology vendors decided not to invest in complex logic to comply with statistical reporting mandates. These new products were like warm Jell-O waiting to be molded: they had the ingredients to  perform policy and claims administration processing, but required heavy configuration and customization, not just to write insurance business (that is, all the transaction sets in a business life cycle—endorsement transactions, change renewals, cancellations, etc.), but to conform to the regulatory  mandates for statistical reporting. It was up to insurance companies to make sure they were covered.
In plain terms: many of today’s systems are set up for collecting information, but how they store data on the back end is not designed to meet statistical reporting requirements.

Set yourself up for stat reporting success

In the rush to get new products to market, insurance companies often get caught up in launching their new system (or product or policy) as quickly as possible. Today’s client-server-based systems are not less capable than previous systems, they’re just more malleable. In providing insurance companies with more flexibility, the vendors put the onus on the insurance companies to configure their systems to perform and ensure compliance. Unfortunately, companies tend to focus on business functions (product rating, forms, coverages, claims handling, etc.) and overlook the importance of collecting and formatting specific transaction sets and data points needed to meet regulatory standards. This is why it’s so crucial to consider statistical reporting requirements from the very outset of your new technology implementation. Here are some strategies that work:

  • Involve the right people from the start

Bringing statistical reporting compliance stakeholders to the table late in the game increases the odds of revealing functionality and data needs previously unaccounted in defining implementation specifications. Therefore, it’s important to have statistical reporting subject matter experts work together with experts in rating, underwriting and claims, early in the process to understand what products, coverages and claim events are contemplated and to define the transaction sets and data elements required. 

  • Account for configuration in your budget

Because of the heavy amount of programming required for legacy systems, it was very difficult to ascertain exactly how much was invested in programming for statistical reporting. These days, it’s easier to identify and quantify. Avoid sticker shock on the final project by earmarking a section of the budget for statistical reporting requirements definition, configuration and testing.

  • Clarify your specifications

Identify the statistical file generation processes you’re currently using to inform your needs for your new system. From there, generate a comprehensive list of specifications and make sure they are reviewed by the teams who will be responsible for statistical reporting. Statistical reporting subject matter experts and third-party reporting consultants can come in handy here, as they can make you aware of current industry best practices and other information “you don’t know that you don’t know.”

  • Produce usable test policy data

One part of the transition that is often overlooked is the availability of “production like test data”, essential to ensure completeness in the encoding/transformation process and often required in bureau electronic testing certifications. A number of statistical agents and rating bureaus require you to compare the captured and encoded statistical data (for risks, coverages, policy and claims transactions) to what is being produced on front-end for the insured. That means classifications of business, coverages being offered, rates and premium amounts must be a direct replica on the back end for statistical reporting process. Account for this in your roll-out plan and dedicate appropriate resources for it.

  • Don’t rely on your data warehouse for stat reporting

Data warehouse solutions are typically not architected to satisfy statistical reporting mandates (including rating, premium and claims detail at the line/subline/coverage/transaction level, policy and endorsement form data and onset/offset entries for regular and out of sequence endorsements). Rather than making your data warehouse too complex and robust, let your statistical reporting experts and programmers work with native data that comes from policy and claims administration systems.

Create a comprehensive game plan

Develop a proactive strategy to test how your system will issue policies and transactions once policies become enforced. Don’t make the mistake of testing front-end functionality without an end-to-end review of how those policies and claims get formulated in comparison to the statistical data that you will also be collecting on the back end.
Involving an outside insurance reporting and development consultant to guide you through the process can be especially valuable here. At Perr&Knight, we offer workshops as a part of our Statistical Reporting Solution service offering. These workshops involve all relevant stakeholders and cover key topics that will inform the game plan that guides you forward.
In these multi-day workshops, we discuss with your teams the interlacing of statistical reporting file creation and testing processes into your information technology objectives, the risks associated with delivering an improved statistical reporting capability, and the coordination of your team and third-party participants to schedule projects related to the implementation of an enhanced statistical reporting solution. The final deliverable to you is an evaluation of strengths, potential vulnerabilities, and a plan for moving ahead that includes clear roles and responsibilities, cost projections and duration estimates. Whether you decide to partner with us or not, you end up with impartial strategy for implementation that you can use as a roadmap.
Because statistical reporting is not seen as revenue-generating aspect of the business, it’s often overlooked during technology development. However, doing so only short-changes you on the back end of your project implementation, as teams scramble to retrofit new systems to meet statistical reporting mandates. Instead, keep statistical reporting requirements in mind straight from the start and save yourself the headache of having to go back and make costly corrections – or being fined for non-compliance.

Want to discuss how to make statistical reporting more manageable for your in-house staff? Our insurance technology experts can help.

InsurTech: The New Frontier for A&H

As troves of data and lightning-fast processing capabilities become increasingly available to insurance companies, cumbersome manual processes are being replaced with faster, more advanced data capture and analysis. The applications for property and casualty insurance, particularly with personal home and auto coverage, were evident straight away; therefore, P&C providers quickly began utilizing innovative technologies from InsurTechs to streamline their workflows, increase rating accuracy, and improve the customer experience.
These technologies are now starting to expand to additional insurance types, ushering in an exciting new era for accident and health coverage providers as well.

InsurTech’s new tools and new opportunities

As millennials and Gen Z buy homes, start families and advance their careers, their needs for insurance increase. However, these emerging customers are unwilling to compromise on the speed and accessibility of any products they buy – including insurance. Therefore, the traditional method of over-the-phone insurance sales or person-to-person broker relationships no longer apply. These customers demand control, transparency, and ease. They want to complete transactions with a few clicks.
They are also accustomed to an unprecedented level of control and customization in their own lives. Non-traditional career trajectories, home-ownership as a second income stream, greater flexibility with travel and work schedules…all add up to a clientele that demands fast, flexible coverage that conforms to their specific needs. This often means shorter coverage periods, specific add-on coverage, and instant payment – again, all accessible via website or smart phone app.

The changing face of A&H

Traditionally, insurance product development for accident, health and travel has adopted a “one size fits” all approach, offering protection that covers a wide variety of scenarios over an extended period of time. However, new technologies enable A&H coverage to achieve an entirely new level of customizability that can provide customers with exactly what they need, only when they need it. Some forward-thinking examples of InsurTech applications for A&H that we have seen include:

  • Travel Insurance
  • Short-term Accidental Injury coverage for specific activities
  • Customizable Supplemental Health Insurance plans such as Critical Illness
  • Major Medical price transparency comparisons
  • Health benefits packages for gig economy workers

This level of tailoring serves customers more effectively, generates new product potentials, and creates efficiencies that ultimately lower internal operations costs for insurance companies.

Apps, IoT and AI – oh my!

InsurTechs have evolved many aspects of today’s insurance industry, but we have seen the most advancement to A&H in the areas of smartphone apps, the Internet of Things (“IoT”), and Artificial Intelligence.
Insurance companies are finally beginning to recognize the value of smart phone apps in connecting with their customers. Mobile technologies are invaluable to insurers, enabling more efficient product marketing, a direct point of sale, and the ability to collect data from wearables. These streamlined products and advanced data collection can reduce or even eliminate the need for underwriting. The result for insurance companies: more efficiency for a lower cost.
“Smart devices” that connect to the internet and transmit data over a network are known collectively as the Internet of Things. These devices work quietly in the background to collect and transmit data that can help insurers provide more accurate premiums to customers. Some major medical insurance companies offer incentives such as premium discounts or gift cards for meeting exercise goals while wearing specific devices (think: Fitbit trackers). Insurers can now tie premiums and rewards to real data, not theoretical projections.
Finally, artificial intelligence (or “AI”) is releasing insurers from burdensome manual processes. These technologies have the ability to learn and reason, freeing up their human counterparts to focus on areas that require more complex reasoning or subtle discretion. Insurance companies have successfully used AI to develop chatbots that streamline the customer service experience and applied machine learning to build more accurate algorithms and models for analyzing data. By applying machine learning to predictive analytics, insurance companies can analyze key consumer data claims risk, fraud detection, anticipated demand for a new product, claims processing and underwriting. This could lead to better rate adequacy and a better overall risk profile.

Control the risks

Emerging technologies are already transforming the insurance industry, but regulation is still woefully behind the curve. Though coverage offerings are more flexible than ever, insurance product development is still subject to a rigid regulatory environment. Regulation of coverage periods, marketing materials, and underwriting processes are still rooted in traditional ways of thinking.
Additionally, InsurTechs may bring the technological expertise, but they often lack industry-specific knowledge. They usually do not even have an underwriting company or reinsurer to take on the insurance risk. This can come back to haunt you if you’re not careful. With this in mind, it’s smart to connect with an experienced independent insurance product development partner to manage regulatory requirements as you incorporate new technologies into your product suite. Their expertise regarding the jurisdiction-by-jurisdiction requirements will be invaluable as you head into the approvals process.
InsurTechs are set to make sweeping changes across the insurance industry as their technologies provide opportunities for insurance companies to respond to never-before-seen coverage needs. These innovations are not trends – they’re here to stay. As data collection and analysis evolve, A&H insurers are positioned to develop systems and products that feature faster policy uptake and fulfillment,  greater flexibility in coverage, and increasingly targeted customer service.

Want to know more about how technology can advance your A&H offerings? Our team of insurance and actuarial experts can help.

Common Mistakes When Pricing Long-Term Contracts

Developing pricing for long term contracts, specifically auto warranty, poses a tricky challenge for insurers. Determining rates for losses that will not occur until three, five, or seven years into the future requires balancing multiple factors to help ensure profitability and appropriate matching of premium earnings and future losses.
Auto warranties, supplemental tire and wheel coverage, guaranteed auto protection (“GAP”), and other long-term contracts require careful actuarial analysis of multiple variables. Mistakes can be costly – and won’t become apparent until well into the future.
Luckily, by avoiding some of these common mistakes, you can develop pricing for long term contracts that protects your customers and keeps you in the black.

Best in class rating manual structure / pricing flexibility

The long-term contract space, specifically for auto warranty, is much more competitive than ever before, as many insurers and InsurTech companies create brand new programs to corner a piece of this market. Therefore, in order to remain competitive and profitable, insurers must achieve as much flexibility on rating plans as possible. Greater flexibility means you have a higher chance of achieving profitability from the get-go without having to continually refile your rating plans to adjust rates.
Working with actuarial experts who apply expertise with long-term contracts across multiple states can dramatically enhance your pricing process. Actuarial consulting experts can develop a factor-based manual that makes it significantly easier to understand the base rates, rating factors and the impact of rate changes on future policyholders. Determining actual relativities for the main rating variables, along with associated base rates, can turn those old school 500-page “rate cards” into concise rating plans, lessening the time drain on your staff for review and understanding of the material as well as reducing the likelihood of erroneous price quotes and premium reversals.

Misjudging your competition

Competitive analysis provides both a starting point and a point of comparison for your rating plans. It’s a valuable component of the big picture. In addition to jurisdictional and coverage plan comparison, there are two lesser-known areas where you may not be obtaining a true sense of how your pricing stacks up against the competition for auto warranty business.
Less experienced folks in this space may compare rates and factors without thoroughly examining the class plan (actual vehicles) to which these factors are assigned. Not everyone assigns auto classes the same way, so it’s crucial to confirm that you’re looking at comparable plans.
Differences in individual components covered in vehicle service contracts can also throw off the accuracy of your competitive analysis. In order to achieve a true apples-to-apples comparison, you must drill down into individual components of each vehicle service contract to make sure that coverages align.

Incorrect profitability analysis

While you may see your market share rise quickly in this space from a balance sheet perspective, in order to understand profitability, you must earn premium appropriately over the life of the long-term contract. Too much upfront premium earnings may lead you to believe that your loss ratio is strong, but when earned premiums start to slow and losses begin to stack up – there is little that can be done to course-correct at that point. It’s imperative to track your earning patterns alongside your loss development to maintain a consistent loss ratio over time.

Rate level indication inaccuracies

Relying solely on an overall rate level indication can paint an incorrect picture. For example, development of losses will vary considerably on whether a vehicle is new versus used. Similarly, with comparing new cars with say 0-10,000 initial miles versus “new” vehicles with 24,000 to 36,000 initial miles. The rate level indications are generally very different for numerous combinations of new/used, term/length of the contract and initial mileage of the vehicle. It’s important to understand how to best break out each one in order to achieve accurate rate level indications as well as balancing homogeneity and credibility in your data.

Not peer-reviewing your work

If you’re not already writing business in this space, much of the above is likely not apparent. As a result, you may inadvertently begin writing a significant amount of “bad” business while other insurers are steering clear. Even if you have been writing certain types of extended service contracts, it’s easy to fall into oversights that could result in leaving money on the table. Experienced actuarial consulting partners can provide an unbiased, fresh perspective on your work, taking into account product expertise, state-by-state knowledge and a deep understanding of rating plans and rate flexibility to ensure that your rates are reasonable for the associated risk.
As competition in this space rises, insurers are rushing headlong into product offerings that might end up costing them dearly down the line. The old saying, “You can’t fix old business” has never been more applicable than to long-term contracts, because the bottom line is: you’re on the hook until the end of the contract. However, by carefully analyzing each element in your rating and working with an experienced actuarial team comprised of subject matter experts, you can sidestep the mistakes outlined above and develop a proven, competitive and profitable product.

Are your extended service contracts priced correctly? If you’re writing new business or want to double-check current offerings, the actuarial experts at Perr&Knight will let you know if you’re on the right track.

Predictive Modeling: 5 Benefits of an Independent Review

The practice of predictive modeling is a powerful tool for risk assessment for today’s insurance industry. What once was considered a new technique for insurance pricing is now getting utilized in all aspects of the industry.
Your models are only as sound as the industry knowledge that goes into their development. Lack of complete regulatory support for predictive models has slowed InsurTech companies and carriers on their path for regulatory approval.
Instead of dealing with the expensive and time-consuming fallout of stalled approvals, it makes more sense to get ahead of potential pitfalls by investing in an independent review of your model from experienced insurance actuarial consulting experts.
Here are five reasons an independent review of your predictive model is worth the investment.

1. Discover your model’s strengths and weaknesses

Independent review from actuarial consulting experts will reveal areas where your model can benefit from improvement as well as verify its biggest benefits. A review that combines proven industry benchmarks with professional actuarial judgment will surface erroneous assumptions, incomplete support and lead to model improvement.

2. Comply with state regulations

Many predictive models have been rejected by state insurance departments due to lack of compliance in that jurisdiction. States have their own unique regulation and you want to be prepared. By partnering with an independent reviewer who knows the nuances of each state’s regulatory process, you’ll strengthen your chance of approval.

3. Strengthen your case with key decision-makers

Achieving buy-in from the customer is crucial when marketing an InsureTech predictive model to insurance carriers. Though your model may perform impeccably, if your company has a limited track record in the insurance industry, it may be a hard sell to the carrier’s executive team. Getting an independent review with comprehensive documentation will demonstrate to decision-makers that your product has been carefully evaluated by insurance industry professionals. This vetting of your model and accompanying written proof may be the deciding factor between your product and a competitor’s.

4. Increase your speed to market

Presenting your model to regulators without thorough pre-submission scrutiny may reveal surprise shortcomings. Discovering these deficiencies while your model is deep into the review process adds unnecessary time. It’s much smarter to pressure-test your model before submitting to state insurance departments to speed up approval for your model’s implementation.

5. Trust in your results

Your data may support strong predictors used in your model, but to be truly effective, results must be combined with subject matter expertise. Insurance experts who understand all steps in the insurance process give you insights for model improvement.
High level assessment of your model’s viability, paired with detailed scrutiny from subject matter experts who specialize in insurance, is a smart way to protect your investment. An independent reviewer will ask tough questions, and follow best practices for predictive modeling in order to assess your methodology to add credibility and strength to your work product. It’s like investing in “insurance” for your insurance product.

Get your independent predictive model review today! Perr&Knight’s experienced actuarial consulting team can help.

Top 4 Considerations for Building a Robust Commercial Lines Rating Plan

Compared to personal lines, commercial lines risks have larger policy premiums, more complicated coverage, and higher limits. Commercial lines risks are also less homogeneous than personal lines risks. Consequently, individual underwriting is often used and there is a greater need for flexibility in pricing these risks.
That said, with some exceptions, commercial lines rates are subject to filing and Department of Insurance (“DOI”) acknowledgment or approval. For this reason, it is advantageous for the commercial lines insurer to incorporate rating flexibility in their commercial lines rate manuals.
Here we will examine the top four considerations for building a flexible and robust commercial lines rating plan.

Schedule Rating/Individual Risk Premium Modification (“IRPM”)

Schedule Rating/IRPM Plans are one of the most common means of achieving greater flexibility in commercial lines filings. Further, they are allowed in almost all states. The range of flexibility that can be achieved through schedule rating varies by jurisdiction. While many states allow overall schedule rating debits and credits of +/-25%, many other states allow a larger overall debit and/or credit. That said, some states impose different levels of flexibility for each individual characteristic while some states have other requirements (for example, eligibility criteria). A review of your Schedule Rating/IRPM Plan can help ensure that you are achieving maximum rating flexibility via this highly accepted rating tool.

Tiering

Another way to achieve flexibility in a commercial filing is to include tiering. Tiering refers to rating manuals that contain more than one set of rates to address different pricing levels associated with different levels or tiers of risk. Tiering is more common with Standard commercial lines (e.g. Commercial Auto, Commercial Property, General Liability, etc.) than with Specialty lines (e.g. D&O and Excess Liability). There are two types of tiering:

Intra-company tiering –A single company includes multiple tiers within a single program (e.g. Preferred, Standard, Non-Standard, etc.). Depending on various criteria, a risk might be assigned to a tier with a lower or higher rate.

Inter-company tiering –An insurer group uses different affiliated underwriting companies to accommodate the above-referenced tier structure.

Tiering is allowed in all states for most Standard commercial lines with some exceptions. While generally accepted for most Standard commercial lines, states differ regarding the filing of applicable underwriting criteria and some even limit the characteristics that can be considered.

Ranges of rates or rating factors

While tiering is more commonly applied to Standard commercial lines, ranges (sometimes referred to as guide (a) rating) are more common with Specialty commercial lines. With ranges of rates or ratings factors, an underwriter chooses a rate or rating factor from the filed range. While many states allow ranges, some states strictly prohibit ranges and others allow with certain limitations or additional requirements.

Individual Risk Rating

Individual Risk Rating, also known as (a) rating and/or Refer to Company rating, refers to those instances where manual rates are not used to determine a risk’s premium. Instead, underwriting judgment is used to evaluate the unique characteristics of the risk and to determine the final premium. This may also include a review of a risk’s historical experience.
Individual Risk Rating is used in both Standard and Specialty commercial lines. For Standard commercial lines, Individual Risk Rating may only apply to a particular segment of the business whereas it may be used more extensively for Specialty commercial lines. The acceptability of Individual Risk Rating varies by state with some states prohibiting the practice, and others allowing it. However, even for those that allow it, there are additional requirements that may apply by state such as individual risk submission filings, reporting requirements, disclosure requirements, etc.
While there are many tools available that allow for a flexible and robust rating plan, a thorough and thoughtful review of your new or existing rating plan can ensure that you achieve the greatest flexibility while minimizing compliance issues and DOI objections that may result in delays, reduced flexibility, and/or inconsistencies in your plan across various jurisdictions.
Partnering with an actuarial services firm that is familiar with DOI regulations and positions on the above-referenced rating tools can help you optimize the flexibility of your commercial lines rating plan. This flexibility will allow you to more accurately price your product and will allow you to maximize competitiveness while being mindful of the various requirements associated with each pricing tool.

Are you achieving maximum flexibility on your current or new commercial lines insurance product? Our expert actuarial consulting and regulatory compliance teams can help.